Beyond funding: Why every startup founder needs an insurance plan
Most founders are equity-rich and cash-poor, with household finances quietly tied to the venture: personal guarantees on business loans, savings deployed into the company, a spouse’s income covering monthly basics. That structure makes personal term insurance more urgent for a founder than for a salaried peer, not less. If the founder dies, the family inherits illiquid equity and live liabilities at the same moment, and only a large, immediate payout resolves that.
The sizing rule also needs adjusting. The standard guidance of 10-15X annual income understates the need for entrepreneurs who deliberately pay themselves a modest salary. Anchor instead to household expenses, outstanding personal guarantees, and the real cost of the family’s next 15 years. Self-employed applicants should expect income documentation requests, ITRs, and bank statements rather than salary slips, and treat that as an administrative step rather than a reason to postpone.
What Does ABSLI Super Term Plan Offer a Founder?
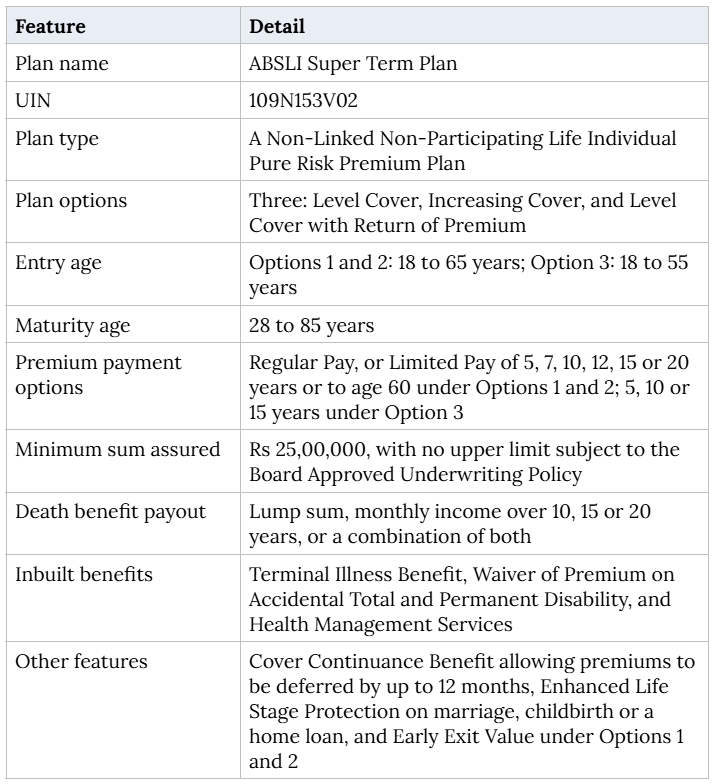
The payout structure matters for founders carrying loan guarantees. A lump sum clears liabilities at once, while the monthly income option keeps a household running for a defined period, and ABSLI Super Term Plan allows the two to be combined, with between 10% and 90% of the sum assured taken as income and the balance as a lump sum.
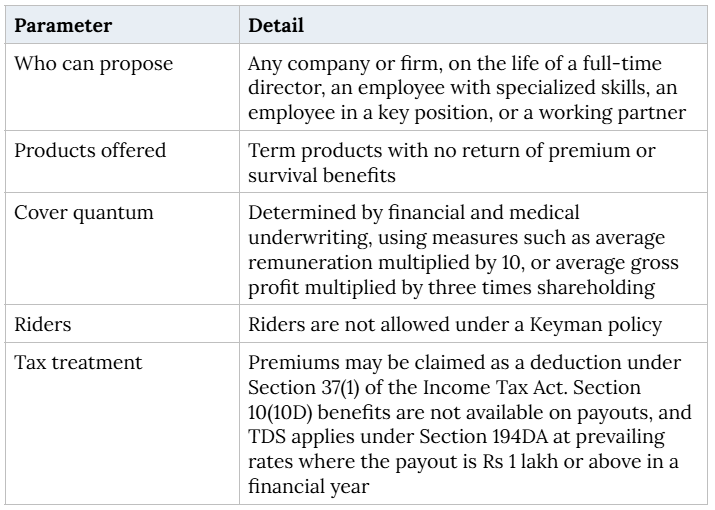
What is keyman insurance and who needs it?
Ask your co-founder a direct question: if either of you died this quarter, does the company survive the next funding conversation? Investors ask themselves the same thing, which is why keyman insurance appears in diligence checklists and shareholder agreements.
ABSLI Keyman Insurance Policy is a life insurance policy purchased by an employer on the life of a key employee, based on the insurable interest an employer has in that person. The payout gives the business capital to stabilise, hire replacement leadership, and reassure the cap table at the moment confidence is scarcest.
For partnership firms, ABSLI Partnership Insurance Scheme addresses a related risk: on the death of an insured partner, the firm has liquidity available to purchase the deceased partner’s share, so working capital is not diverted and surviving partners are not required to bring in additional funds. Cover is assessed against the firm’s net worth, including each partner’s share of capital, share of profit and share in goodwill.
How does employer-employee cover work for a startup team?
This is the part that belongs in your next HR planning cycle. Under ABSLI Employer - Employee Insurance Scheme, the employer proposes and owns a policy on the life of an employee, and assigns it to the employee after a defined period. Assignment can be absolute, transferring ownership at issuance, or conditional, transferring ownership once terms set by the employer are met. Any company, proprietorship firm, LLP, trust, NGO or society with a genuine employer-employee relationship is eligible.
The return on that spend is talent economics. Startups ask employees to accept risk, and benefits that protect an employee’s family are how a company signals it takes that trade seriously. The structure also matures with the company: the arrangement that covers a handful of employees becomes the foundation of the full benefits programme a later-stage HR lead will build. All products other than child plans can be offered under the scheme, and all riders other than Waiver of Premium can be attached.
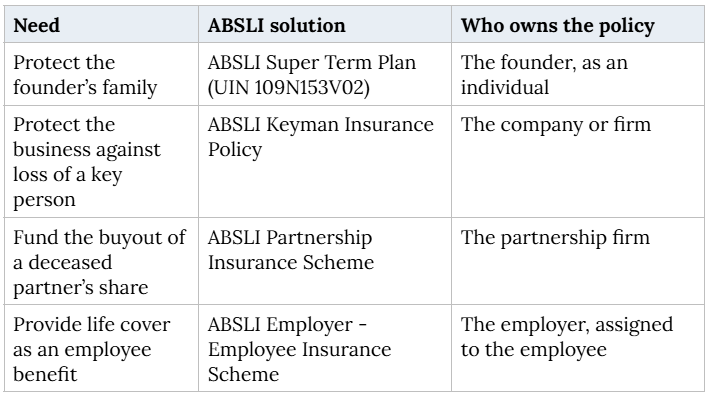
Which ABSLI solution fits which need?
What should a founder do first?
- Buy personal term cover now, sized to household expenses and outstanding personal guarantees rather than declared salary, while age and health are on your side.
- Add keyman cover once the company has revenue or a valuation worth protecting.
- Put employer-employee cover in place for the team as an early, deliberate retention investment.
- Review all three annually, because cover set at seed stage rarely matches the liabilities of a Series A company.
- Disclose health, income and business details fully at proposal stage, since complete disclosure is what ensures a smooth claim later.
Key Takeaways
- Founders need personal term cover first, sized to household expenses and personal guarantees rather than declared salary.
- ABSLI Super Term Plan offers three plan options, entry from 18 to 65 years and a minimum sum assured of Rs 25,00,000.
- ABSLI Keyman Insurance Policy allows a company to insure a key employee, with the company as the policy owner.
- ABSLI Partnership Insurance Scheme helps a firm fund the purchase of a deceased partner’s share.
- ABSLI Employer-Employee Insurance Scheme lets an employer insure employees as a welfare and retention measure.
- Premiums paid under Keyman and Employer-Employee arrangements may be claimed as a deduction under Section 37(1), subject to applicable tax laws.
- GST is not applicable on individual life insurance premiums.
- ABSLI settled 98.86%* of individual death claims in FY26.
Disclaimers:
*Individual death claim settlement ratio for FY 2025-26, as per annual audited figures submitted to IRDAI. Tax benefits are subject to prevailing tax laws and conditions; please consult a tax advisor. Business insurance terms, eligibility and cover quantum depend on underwriting and on the profile of the firm. Please read product brochures carefully before concluding a sale.
Under Keyman, Employer-Employee and Partnership arrangements, several ABSLI Super Term Plan features do not apply, including Cover Continuance Benefit, Early Exit Value, Instant Payment on Claim and Waiver of Premium on Terminal Illness or ATPD. Terminal Illness Benefit and Health Management Services do apply.
Aditya Birla Sun Life Insurance Company Limited, Registered with Insurance Regulatory & Development Authority of India (IRDAI) as Life Insurance Company. Registered Office: One World Center Tower 1, 16th Floor, Jupiter Mill Compound, 841, Senapati Bapat Marg, Elphinstone Road, Mumbai - 400013. Toll free no. 1800-270-7000. https://lifeinsurance.adityabirlacapital.com/ | care.lifeinsurance@adityabirlacapital.com | CIN: U99999MH2000PLC128110 | Registration No. 109.
"BEWARE OF SPURIOUS PHONE CALLS AND FICTITIOUS / FRAUDULENT OFFERS" IRDAI or its officials do not involve in activities like selling insurance policies, announcing bonus or investment of premiums. Public receiving such phone calls are requested to lodge a police complaint.
For more details on risk factors, terms and conditions please read the sales prospectus carefully before concluding a sale. Life insurance coverage is available in these products.
UIN: ABSLI Super Term Plan (UIN 109N153V02)
ADV/9/26-27/700
(Disclaimer: The views and opinions expressed in this article are those of the author and do not necessarily reflect the views of YourStory.)
This content is published by YourStory and has not been created or edited by Hello Headlines. View original